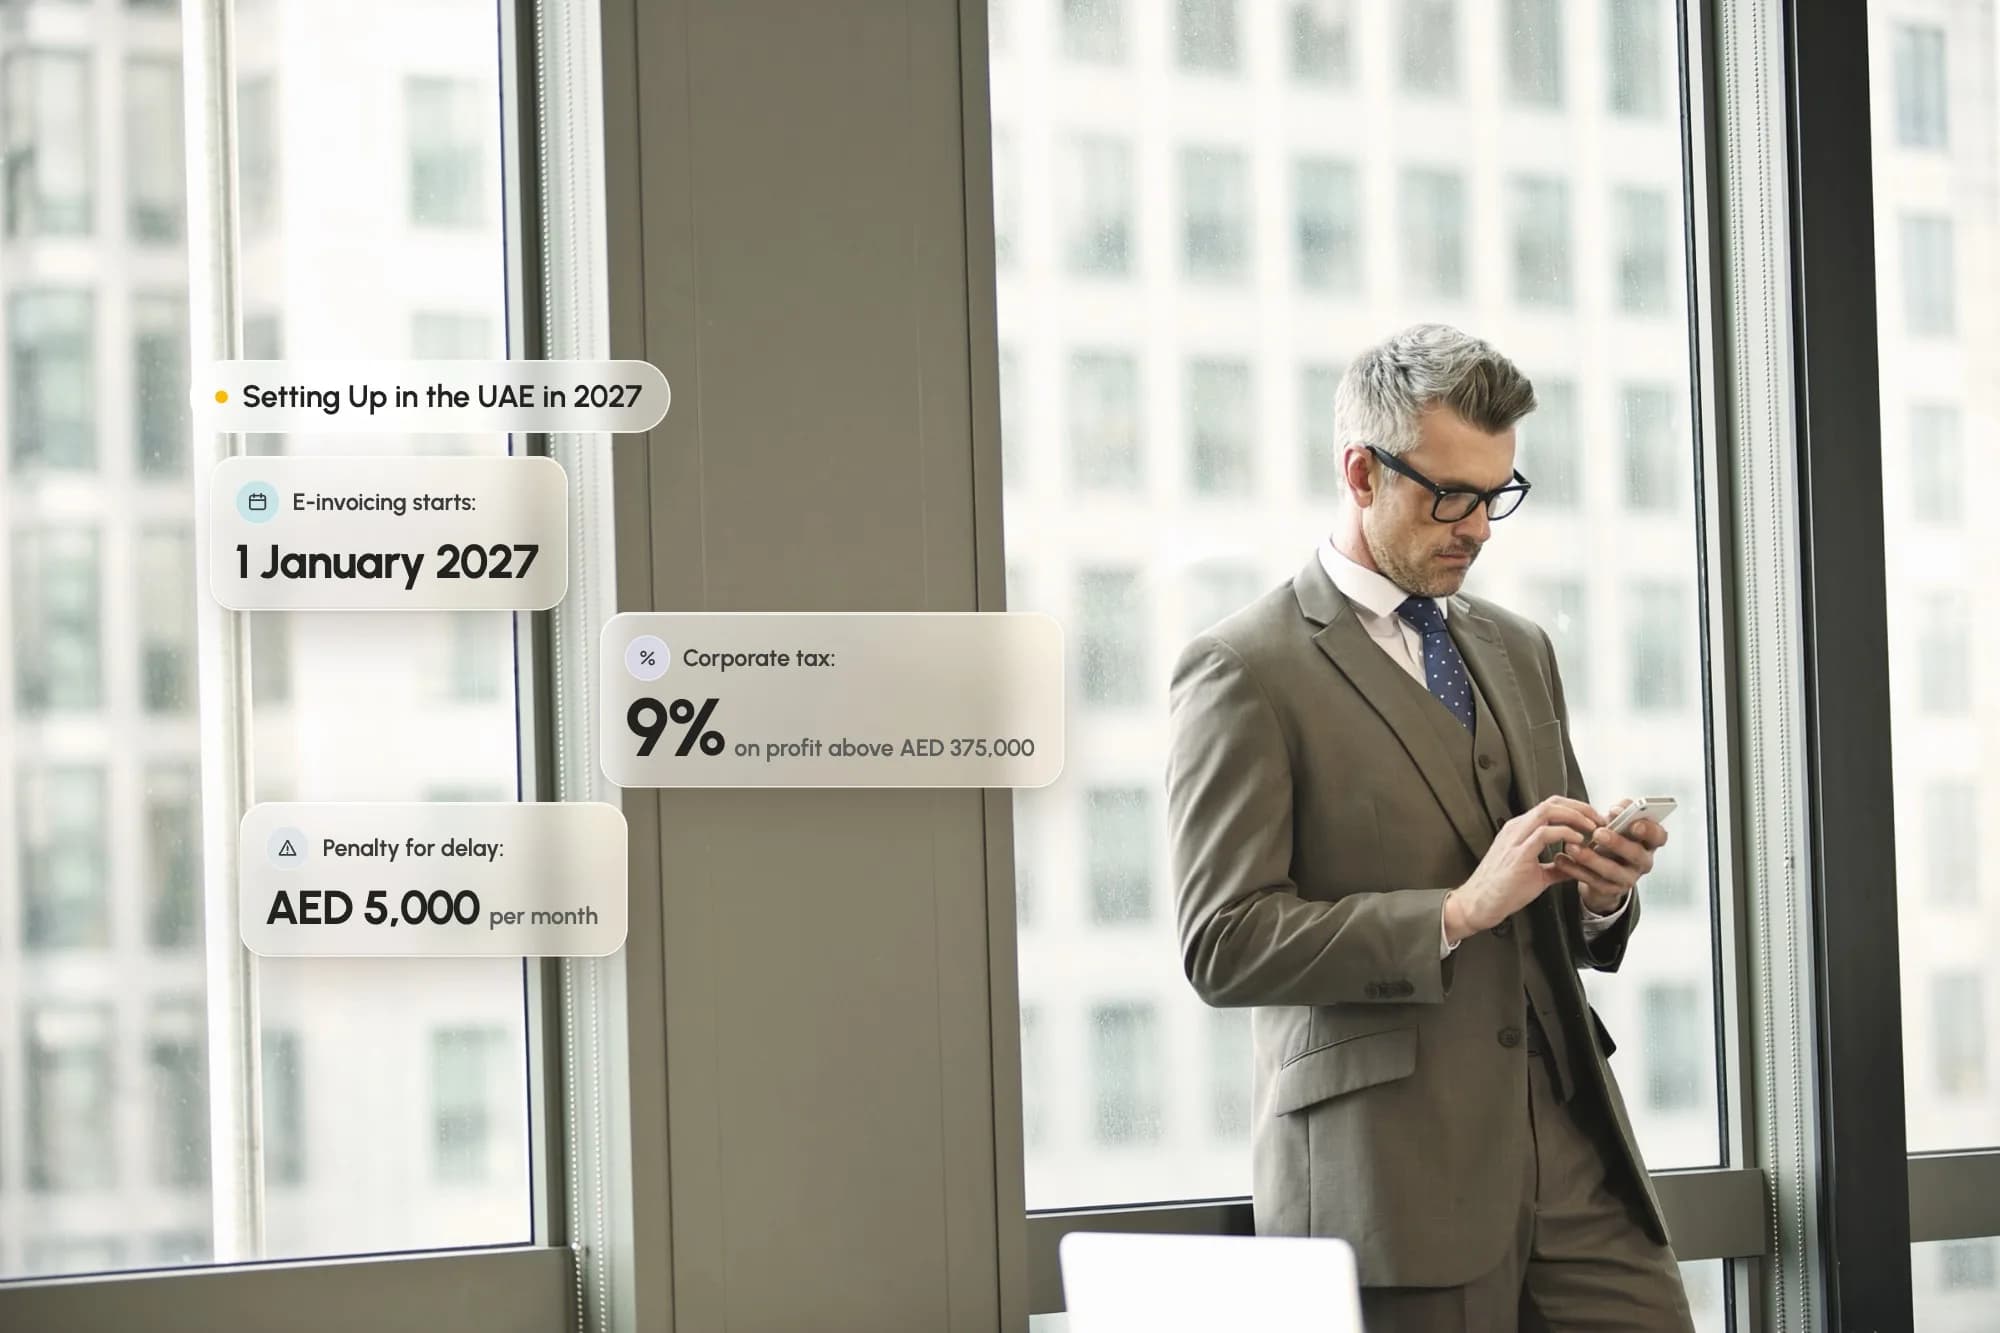
A business set up in UAE in 2027 starts trading under a compliance calendar that earlier cohorts did not face. Corporate tax applies at 9% on profit above AED 375,000. VAT registration is mandatory once taxable supplies pass AED 375,000 a year. Mandatory e-invoicing starts on 1 January 2027 for taxpayers with revenue of AED 50 million or more, and on 1 July 2027 for all others.
That means a new business begins trading inside the e-invoicing regime, or within months of it. Each obligation is easier to meet when it is planned at set-up, and easier still when one team manages all of them. This article sets out the obligations, the set-up decisions that shape them and how HLB HAMT’s Business Consultancy team handles corporate compliance under one roof.
The obligations a new UAE business takes on
Obligation
Key figures
Applies to
- Corporate tax
- 9% on profit above AED 375,000. 0% on qualifying income for a Qualifying Free Zone Person
- Mainland and free zone companies
- VAT
- Mandatory registration above AED 375,000 in annual taxable supplies
- Taxable businesses
- E-invoicing
- 1 January 2027 for revenue of AED 50 million or more. 1 July 2027 for revenue below AED 50 million
- Domestic business-to-business and business-to-government transactions, regardless of VAT registration
- E-invoicing penalties
- AED 5,000 per month for delay in appointing an Accredited Service Provider (ASP) or implementing the system. AED 100 per invoice, capped at AED 5,000 per month
- Businesses in their mandatory phase
E-invoicing runs through an ASP on the Peppol PINT AE standard, overseen by the Ministry of Finance. Business-to-consumer transactions are out of scope.
Four set-up decisions that shape compliance
01
Jurisdiction
The choice between a free zone and the mainland changes the tax position and the customers a business can serve. A free zone company earns 0% only on qualifying income, and income from mainland customers is generally non-qualifying.
02
Licence activity
The licence should match the services the business invoices for. A mismatch can affect tax status and banking.
03
Ownership and entity structure
The structure affects group reporting, access to reliefs and the cost of any later restructuring.
04
Accounting and invoicing systems
The system must capture the mandatory e-invoice fields and connect to an ASP. A system chosen without this in mind may need replacing within the first year.
All corporate compliance under one roof
A new business usually works with several providers: one for formation, another for accounting, another for tax. Each holds part of the picture. HLB HAMT’s Business Consultancy team brings these services together, from the first structuring decision through to ongoing compliance.
Structuring and jurisdiction selection
Comparing free zone, mainland and dual licence options against the activity, customer base and tax position.
Company formation and licensing
Managing the application, documentation and approvals.
Accounting and bookkeeping
Setting up records and systems that meet corporate tax and e-invoicing requirements.
VAT and corporate tax
Managing registration, returns and filings under the chosen structure.
Audit and assurance
Supporting statutory and compliance audit requirements as the business grows.
E-invoicing readiness
Aligning systems, data and processes with the 2027 requirements.
What one team changes for the business
One point of accountability.
A single team owns the compliance calendar, so no deadline falls between providers.
Consistent data.
Accounting, tax and invoicing records come from the same source, which reduces errors and rejected invoices.
Decisions made in context.
The team can see how a structuring choice affects tax, audit and invoicing before it is made.
Lower cost of change.
A business that builds compliance into its set-up avoids replacing systems and restructuring later.
Why e-invoicing belongs in the set-up conversation
For a business set up in 2027, the e-invoicing go-live is either imminent or already in force. An ASP must be appointed before the go-live date, and the monthly penalty continues until the business complies.
Retrofitting an invoicing process while trading is slower and carries penalty risk. A business that builds the process into its accounting set-up avoids that cost.