

AML/CFT policies, procedures and AUPs
AML/CFT stands for Anti-Money Laundering and Countering the Financing of Terrorism.
It is a set of regulatory measures and procedures implemented by Financial Institutions and Designated Non-Financial Businesses and Professions to prevent money laundering and terrorist financing activities.
Our team of compliance and risk management specialists offers a comprehensive range of AML services tailored to your specific compliance requirements to support you in overcoming the difficulties and complexity that AML CFT laws pose for your company.
- 25+
- years in the UAE
- 4,000+
- clients helped
- 300+
- in-house professionals

- 8thGlobal rank, HLB International
- 155Presence in countries
- 58,538People strong
- 1398Offices all over
The AML Policy and Procedures lay down the main principles for effective prevention and control, providing protocols for examining and reporting potential ML/TF-related actions.
Our expert team can assist you in developing tailored AML/CFT policies and procedures and any related rules required by the supervisory body.
At HLB HAMT, we pride ourselves on providing exceptional services for Anti-Money Laundering (AML) and Combating the Financing of Terrorism (CFT) compliance. With our team of experts who possess vast industry experience, in-depth knowledge, and specialized skills, we deliver a comprehensive range of AML/CFT services that meet the unique needs of each of our clients. Our dedicated AML/CFT compliance professionals and analysts work collaboratively to ensure that we provide top-notch services to guide you towards achieving your compliance goals with ease.
Protecting your business through comprehensive AML compliance in the UAE
We provide professional services to assist you in developing and maintaining Anti-Money Laundering (AML)/Countering Financing of Terrorism (CFT) policies, and procedures. Financial institutions and DNFBPS must have comprehensive AML CFT policies based on their ML/FT risk assessments per national and international laws and regulations.
AML CFT procedures must be based on the UAE’s current AML/CFT laws, regulations, notices, and standards as well as global best practices and guidelines from organizations like the Financial Action Task Force (FATF).
Risks faced by the business
- 01Damage to reputation
- 02Loss of business, account seizures associated with money laundering, and fines are possible losses.
- 03Future business growth and success may be affected.
- 04The regulators may withdraw or deny operating licenses.
AML/CFT policies and procedures in the UAE
Written for the authority that supervises you
Mainland and commercial free zones
Real estate brokers, dealers in precious metals and stones, accountants and company service providers answer to the Ministry of Economy and Tourism; lawyers and notaries to the Ministry of Justice. The manual follows their guidelines and circulars.
Banks, insurers and finance firms
Supervised by the Central Bank of the UAE, with securities firms under the federal capital markets regulator. Their sector guidance and thematic reviews set the detail your procedures must meet.
Virtual asset firms in Dubai
Licensed by the Virtual Assets Regulatory Authority. The manual answers to its rulebook and to federal law together, including wallet screening and travel-rule checks.
DIFC firms
Supervised by the Dubai Financial Services Authority. The framework follows its AML module, with the business risk assessment, the MLRO regime and the annual AML return, alongside federal law.
ADGM firms
Financial firms follow the FSRA's AML rulebook and non-financial businesses are supervised by the ADGM Registration Authority, both on top of federal law.
Anti-Money Laundering (AML) consulting services we provide
26
areas covered across the six frameworks we draft with you.
- 4 areas
Enterprise-wide risk framework
- Market Risk
- Operational Risk
- Reputational Risk
- Regulatory Risk
- 5 areas
RBA-based AML CFT risk framework
- Customer
- Product
- Jurisdiction
- Delivery channel
- Counterparty
- 5 areas
Fraud prevention and whistleblowing
- Actions constituting fraud
- Confidentiality
- Investigation duties
- Reporting
- Legal intervention
- 3 areas
Customer protection and transparent framework
- Consumer Education and Awareness
- Business conduct, Market conduct
- Responsible Financing Practices
- 5 areas
Business continuity plan and processes
- Risk Management Plan
- Business Impact Analysis
- Response Time
- Recovery
- Testing
- 4 areas
AML CFT governance framework
- AML CFT Program Design
- Implementation Plan
- KYC, CID, CDD, EDD, KYCC
- Sanctions Compliance Program
What your manual sets out
Risk-based approach
How the business identifies and records its money laundering, terrorist financing and proliferation financing risks across customers, products, channels and countries, and keeps that view current.
Customer due diligence
How customers are identified and verified at onboarding, and how the relationship is monitored after that.
Enhanced due diligence
What triggers closer checks on a higher-risk customer: source of funds and wealth, more frequent reviews and senior management approval.
Beneficial ownership
How you find the people who ultimately own or control a customer, and how your own register is kept up to date.
Politically exposed persons
How PEPs, their family members and close associates are screened, approved and monitored.
Sanctions and freezing
Screening against the UN and UAE local terrorist lists, freezing without delay and reporting a match to the authorities.
Reporting suspicions
The internal escalation route, the compliance officer's decision, filing through goAML and the rule against tipping off the customer.
Compliance officer and oversight
The compliance officer's appointment, independence and authority, and what senior management oversees and is told.
Records, training and audit
Which records are kept and how they are retrieved on request, the training staff receive and the independent audit that tests the programme.
Where the risk allows, it also sets out when simplified checks apply and when you may rely on another firm's due diligence.
A gap review of the manual you already have
What the review covers
- Risk identification
- Customer due diligence
- Reporting and escalation
- Governance and oversight
- Staff training
- Records and retrieval
The gap we find most often: a manual whose legal references are current while its procedures still follow the old framework.
Firms usually ask for a review after a supervisor's inspection notice, when their bank asks for an updated AML policy, or when a new rule arrives and nobody is sure the manual reflects it. We separate new or changed requirements from existing duties that were never put into practice.
You receive a change register linking each finding to its source, the document affected, the control owner and the action that closes it.
Perform strategies for customer due diligence
Fit with the transaction
Ascertain that the customer’s profile is suitable with the real estate transaction’s parameters.
PEP connections
Stay updated for any connections to Political Exposed Persons (PEPs), mainly in the presence of overseas market participants.
Beneficial owners
You must keep a close eye on your client’s beneficial owner’s identification and gather all essential documentation.
Screening and checks
You should have a set procedure in place for screening consumers and run security checks.
Contract structure
You must take account of the legal contract or framework utilised in the trade, as it may lead in the owner’s or source of funds’ identity being concealed.
Although the degree and scope of the dangers presented by the real estate sector and the Licensed Financial Institutions (LFI) differs, they do have some basic traits that LFIs should be aware of and consider. Once you find potential risk consumers, you must monitor their transactions on a frequent basis. You should keep track of how often and what kind of deals they have done. Adopting reliable and accurate internal procedures, restrictions, and processes are some of the most important steps. You must evaluate the success of these policies and make any updates as needed. Any questionable activities must be reported to the Financial Intelligence Unit as soon as you detect them. You must enter and maintain all the critical data for the alleged transaction.
Assistance of HLB HAMT
Why real estate needs controls
The real estate industry plays a significant role in the UAE’s economy. As a result, preventing money laundering is vital. By implementing AML measures with the assistance of expert AML consultant, you will be able to protect your business from any unlawful activity or business connection, as they will be adequately prepared with the correct, essential anti-money laundering controls.
Compliance rests with the firm
Authorities are taking steps to make the sector more monitored. However, it is finally up to companies in the sector to ensure that they are complying with regulations. Using competent advisers, such as HLB HAMT, can ensure that firms are adhering to AML regulations, which will create an additional layer to handle potential issues and protect AML compliance for companies in the UAE.
What you receive
A full documentation set, ready for senior management to approve, rather than a single file.
- AML/CFT policy and procedures manual
- Customer risk rating model
- Due diligence, PEP and source-of-funds forms
- Beneficial ownership templates and register
- Sanctions screening and freezing procedure
- Customer, screening and transaction registers
- Red-flag guidance for your sector
- Escalation route and MLRO decision log
- Training plan and register
- Compliance calendar of recurring duties
Focused reviews alongside the manual
Decisions that sit next to the policy and often need a documented basis of their own.
When simplified checks are allowed
We set the criteria for treating a relationship as lower risk, what staff must still collect and monitor, and the events that send a customer back to standard or enhanced checks.
Relying on another firm's due diligence
A KYC pack from someone else is not a reliance arrangement on its own. We test whether the third party and the activity qualify, how quickly you can get the documents and what stays your responsibility.
Outsourcing an AML activity
We review the provider, the contract and your oversight of the work, and plan how data, open cases and records come back if the arrangement ends or fails.
Turning regulatory change into control updates
Each change is logged with its source, effective date and relevance to your licence, then tracked through the policies, systems, forms and training it touches until the update is evidenced.
Answering a bank's AML questionnaire
We map each question to your policies, registrations and records, so every answer matches how you actually operate. The bank still makes its own decision on the relationship.
How we build your policy
Understand your risks
3 steps
Understand the business
We start from your risk assessment and look at every point where money or value moves through the business.
Review what you have
We compare your current policy, procedures and forms with the law and with how your staff actually work.
Agree the gaps
We take your compliance officer through the gaps before any drafting starts.
Draft the framework
3 steps
Rate your customers
We set how customers are rated for risk: the factors, the ratings, when an override is allowed and what calls for a fresh review.
Draft one framework
Policy, controls and procedures are written together, with an owner for each control and the legal basis for each obligation.
Prepare forms and registers
We prepare the due diligence forms, the registers and a control matrix that go with the policy.
Put it to work
3 steps
Walk it through
We test the draft with the people who will use it, and a second reviewer checks it before it goes for approval.
Approve and roll out
Senior management approves the policy, the sign-off is kept on record and staff are briefed.
Keep it current
We support implementation and training, and agree when the policy will next be reviewed.
Benefits of associating with us for AML/CFT consultancy services in the UAE
Compliance, done efficiently
We recognize the importance of AML/CFT regulatory requirements in today’s world, and our AML consulting services assist our customers in ensuring compliance efficiently and effectively.
A network of specialists
We have a strong network of AML/CFT solution providers, highly qualified specialists and compliance experts that can assist you in responding correctly to AML threats.
Protection from non-compliance
By partnering with HLB HAMT for your AML/CFT consulting requirements, you can be confident that your organization is taking the necessary steps to comply with the relevant regulations in the United Arab Emirates and protect your business from non-compliance.
Any industry, stage or size
Our AML consulting services are tailored to assist customers from every specific industry, at any point of the AML/CFT process, and of any size in efficiently managing the risks of financial crime.
Why AUPs matter
Defined facts for a specified party
An AUP engagement is appropriate when a specified party needs defined facts. The practitioner performs the procedures agreed in advance and reports the results exactly as identified. No audit opinion or assurance conclusion is provided. This precision enables the recipient to evaluate the findings against its own purpose.
- Procedures agreed in advance
- Results exactly as identified
- No audit opinion
A practical tool across the market
In the UAE’s current supervisory climate, AUPs have become a practical tool across the market: supervisors use them to verify remediation without a full re-inspection; correspondent banks use them to underpin relationship reviews; and group functions use them to test local compliance in a defined, comparable way across subsidiaries.
- Supervisors
- Correspondent banks
- Group functions
Our AML/CFT AUP services
Regulator-directed AUPs
Procedures designed to address a supervisor's request, such as remediation validation, sanctions screening coverage or reporting timeliness.
Sanctions screening AUPs
Factual testing of whether customers, beneficial owners, counterparties and payments were screened against the applicable lists and appropriately dispositioned.
CDD / KYC file AUPs
Procedures over defined samples of customer files, testing the presence and adequacy of specified identification, beneficial ownership and risk classification elements.
Transaction monitoring & reporting AUPs
Testing of alert handling against defined criteria, and of STR/SAR filings for completeness and timeliness through goAML.
Correspondent / counterparty assurance AUPs
Procedures designed to satisfy the AML assurance requests of correspondent banks, group head offices or major counterparties.
Training & employee screening AUPs
Verification that specified training completion and staff screening requirements were met for a defined population and period.
Who is in scope and what a procedure can test
Reporting entities
Who the rules apply to
- Banks, exchange houses and finance companies
- Insurers, investment firms and securities brokers
- Virtual asset service providers
- Real estate brokers and dealers in precious metals and stones
- Auditors, accountants and corporate service providers
- Lawyers and notaries for covered transactions
Core obligations
What procedures can be framed around
- goAML registration and reporting
- An enterprise-wide risk assessment, kept current
- A written policy approved by senior management
- Customer due diligence and beneficial ownership
- Sanctions screening, freezing and reporting
- Staff training and independent review
Regulator-required AUPs for exchange houses
- Customer due diligence
- Transaction monitoring
- Record keeping
- Staff AML training
- Internal controls
- Suspicious transaction reporting
- Periodic policy reviews
- Correspondent and third-party relationships
- Sanctions screening
Our approach
Procedures agreed before fieldwork
We define specific, measurable procedures with the engaging party and, where relevant, the intended recipient.
ISRS 4400 discipline
Engagements performed under the international standard on agreed-upon procedures, with the terms, procedures and findings documented to that standard.
Regulatory anchoring
Procedures framed around the specific obligations in Federal Decree Law 10/2025, Cabinet Resolution 134/2025 and the applicable rulebook, so findings map cleanly to compliance requirements.
Factual, exception-based reporting
The report sets out populations, samples, procedures, exceptions and supporting details without an assurance conclusion.
Efficient execution
Structured information request lists and status trackers keep fieldwork tight and predictable.
An AUP or a full independent audit?
Agreed-upon procedures
Narrow-scope AUPs can complete in one to three weeks
Suits
- Remediation validation
- Screening coverage
- File completeness
- Reporting timeliness
Defined matters, tested with procedures agreed in advance and reported as facts. We give no opinion of our own: the party that asked for the report draws the conclusion.
Independent AML/CFT audit
A focused audit of a smaller DNFBP typically runs two to four weeks
Suits
- The independent review requirement
- Testing the whole programme
- A view for the board
- Inspection preparation
Tests whether the programme as a whole is designed well and works in practice, and gives the auditor's own rated findings with a recommendation for each.
Many firms use both: the audit for the whole programme, then an AUP to confirm that specific findings were closed.
Tell us who needs the evidence and what they will do with it, and we will say which one answers the question.
Ask which one fitsAdvisory work is different again: it designs or improves the controls that an audit or an AUP then tests.
What an AUP gives you
Exactly the evidence required
The recipient receives findings on the defined procedures and scope, without unrelated commentary.
Cost-proportionate scope
Targeted procedures cost a fraction of a full-scope audit when only defined areas are in question.
Credibility with recipients
An ISRS 4400 report from an established audit firm carries weight with regulators, banks and group functions.
Responsive timelines
A focused scope can support fixed regulatory, banking or counterparty deadlines.
A clear factual record
An unambiguous baseline for remediation or for demonstrating that remediation is complete.
The scope stays as narrow as the question the recipient needs answered.
Why choose HLB HAMT for AML/CFT AUPs
AML specialist input
Procedures are designed by specialists who routinely audit and assess the relevant AML/CFT controls.
Proven UAE delivery experience
Experience delivering AML/CFT AUPs and findings-based reporting across banks, insurers, investment firms and DNFBPs in the UAE.
Regulator-aligned reporting
Fluency in what CBUAE, FSRA, DFSA, VARA and Ministry of Economy recipients expect a findings report to look like.
Actionable findings workbooks
Colour-coded findings workbooks alongside the formal report, so your team can act on exceptions immediately.
Connected follow-on support
Where the factual findings indicate wider weaknesses, HLB HAMT can separately scope a gap assessment, remediation programme or independent audit.
The procedures you agreed, the facts we found, reported as they are.
Meet the experts
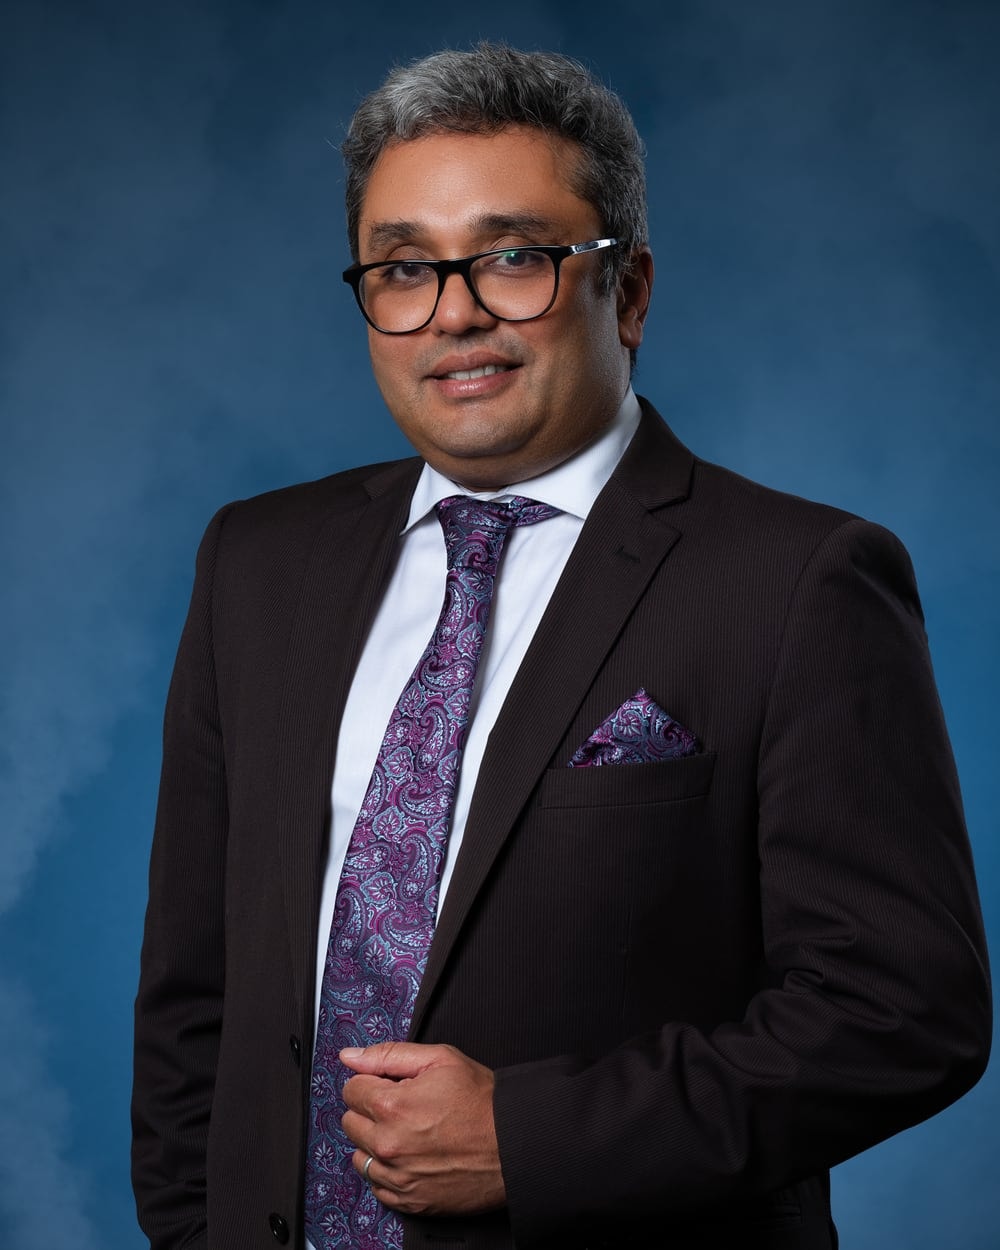
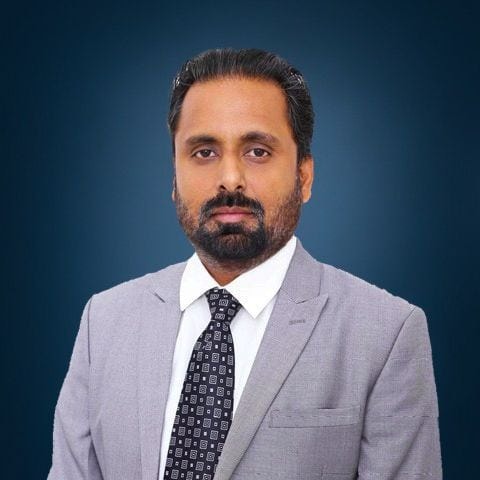
The people who lead HLB HAMT’s AML/CFT policy and agreed-upon procedures work.
Get a policy written for your business
At HLB HAMT, we offer AML Consulting Services to free you from the hassle of AML/CFT Compliance while you start focusing on your primary line of business.
What happens next?
- We review your inquiry.
- We discuss your requirements and the scope of support.
- We agree on the next steps.
FAQ
Frequently asked questions
Contact HLB HAMT
Talk to our AML/CFT team.
Tell us about your business, your supervisor and the policies you have today.
Talk to a team that understands the detail.
For new business enquiries, service questions or an introduction to our specialists, reach us directly or use the form.


Monday-Friday · 7:30 AM-5:30 PM GST
Explore More HLB Business Services
Looking for support beyond AML/CFT compliance? Explore other HLB HAMT services that may match your business requirements.
 Need to assess your money-laundering exposure?Your business-wide ML/TF risk assessed and documented.Enterprise-Wide Risk Assessment (EWRA)
 Does your team know how to spot financial crime?AML/CFT training for boards, staff and compliance teams.AML/CFT Training
- Due for an independent AML/CFT review?Your AML/CFT programme independently tested.AML/CFT Independent Audit
- Need a qualified MLRO?An experienced MLRO for your business, on an outsourced basis.Outsourced MLRO Services
HLB HAMT Insights
Stay Ahead with Our Insights
Insights on AML/CFT compliance, risk and internal audit for UAE businesses, from HLB HAMT's specialists.
