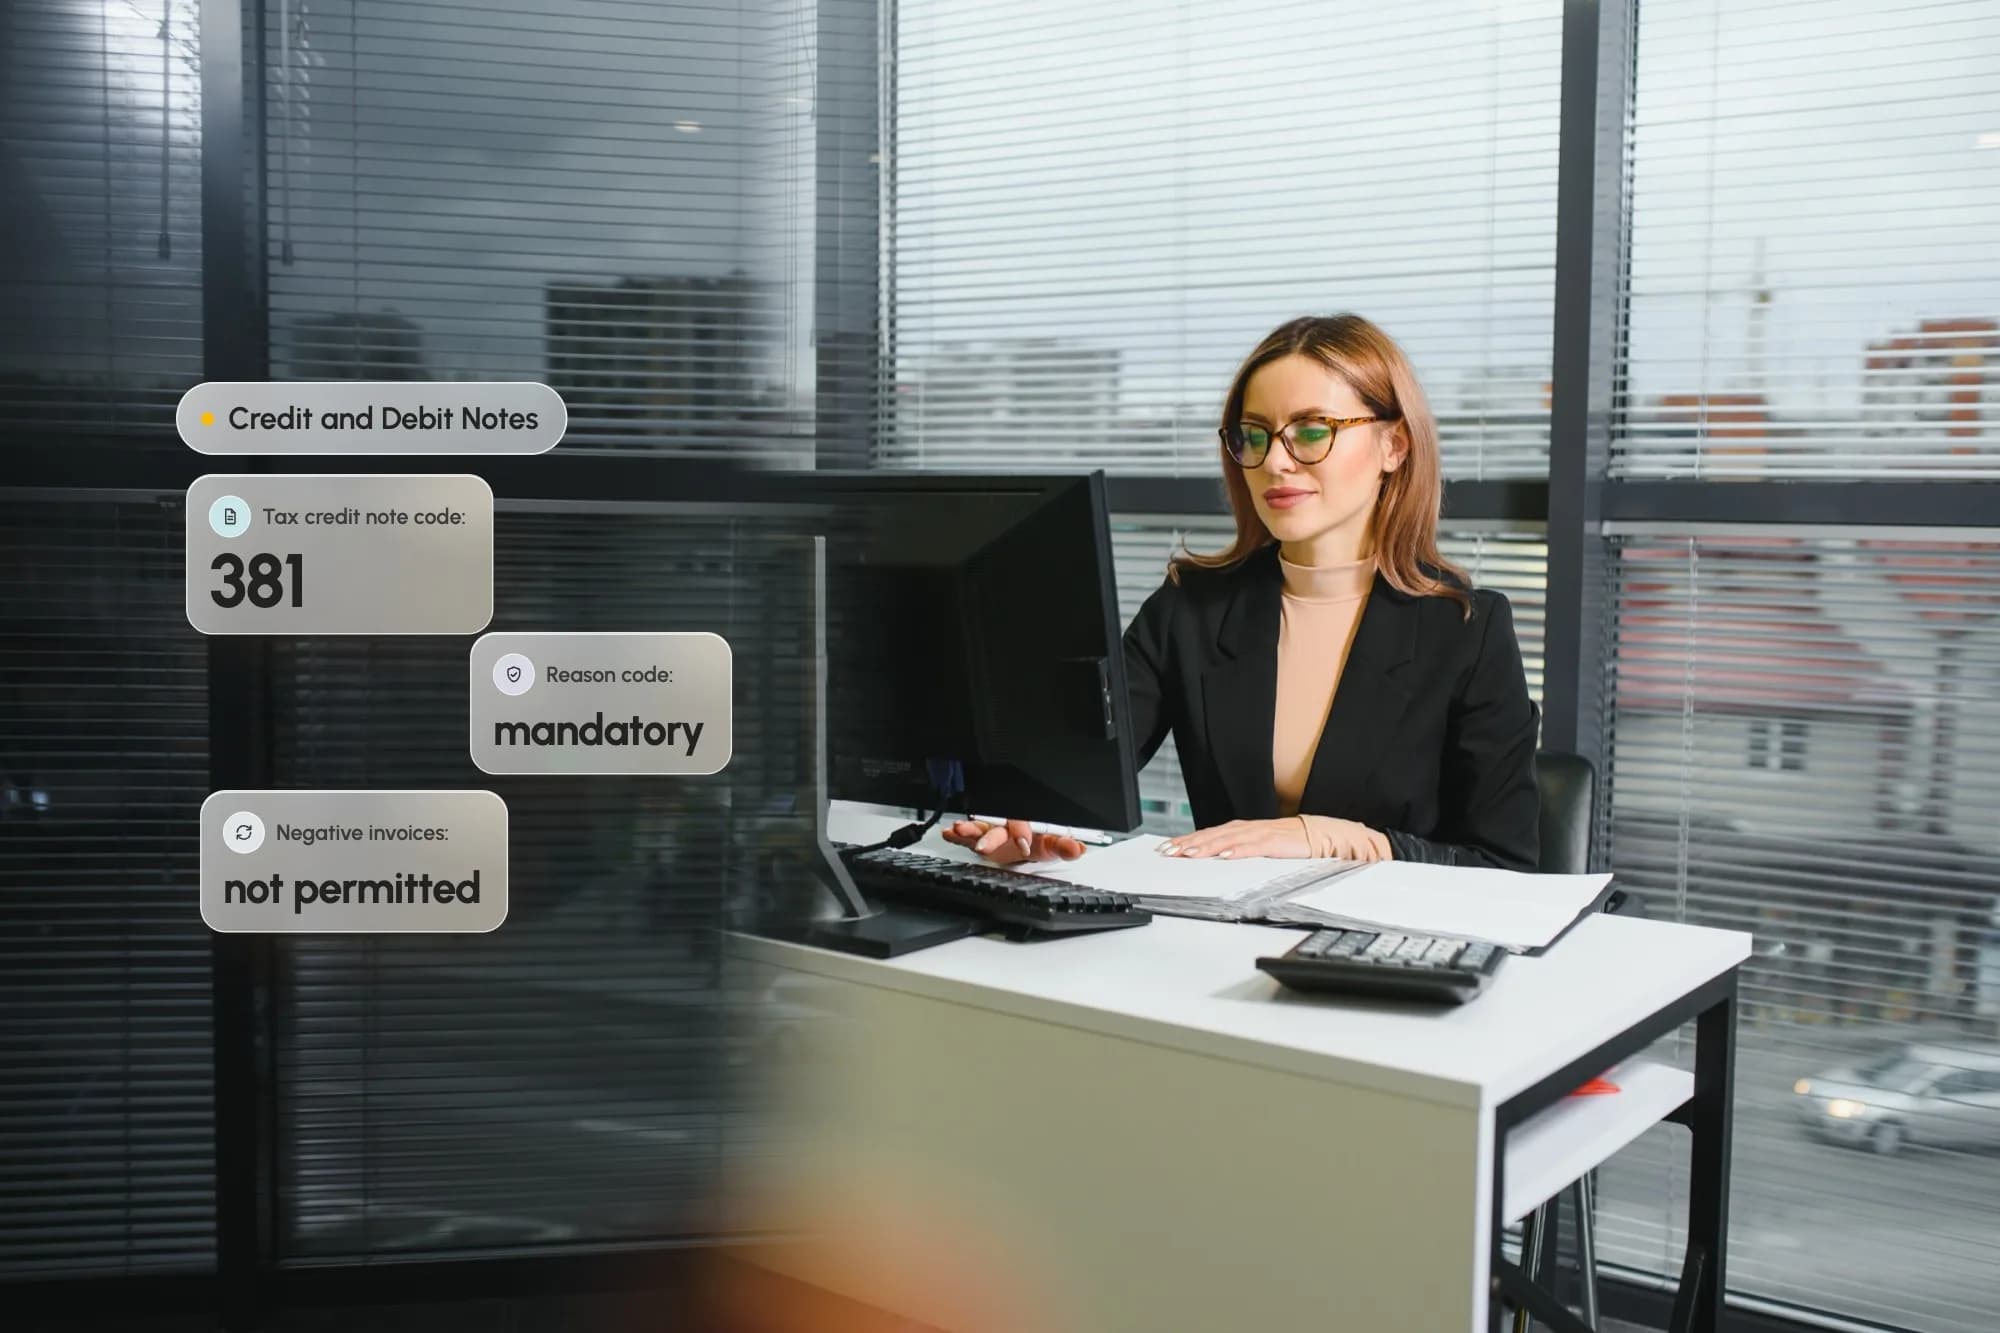
An electronic credit note or debit note must follow the same PINT-AE structure, provider transmission and FTA reporting as an invoice, and it must reference the original invoice it adjusts. You cannot issue a negative invoice to reverse a transaction; the only route is a credit note. A standalone credit note with no origin invoice will not be accepted. The credit note must carry a reason code, use the correct document type code, and be transmitted through your provider within the same timeframes as any other tax document.
Almost every business issues credit and debit notes, for returns, discounts, corrections and cancellations. Under e-Invoicing these become structured documents with strict linkage rules. Here is how they work and where teams get caught out.
The core rule: no negative invoices, no orphan credits
Two principles sit at the centre of this.
First, in the UAE you cannot reverse an invoice that has been issued and received by raising a negative invoice.
The only mechanism is a credit note.
Second, every credit and debit note must reference the original invoice’s unique identifier.
That reference is what preserves the audit trail, and a standalone credit note without an origin invoice is rejected.
There is no undo button, only a forward-correcting chain of documents that all link back to the original.
Document type codes and reason codes
The PINT-AE specification is precise about how an adjustment document is labelled. Two fields do the heavy lifting:
Field
What it must carry
- Invoice type code
- 381 for a tax credit note; 81 for a credit note related to out-of-scope goods or services.
- Credit note reason code
- Mandatory. A code identifying why the note is issued (return, discount, error, cancellation).
- Preceding invoice reference
- The original invoice reference, so the credit note links to the invoice it adjusts.
Specifying the reason for the credit note is compulsory. The preceding invoice reference is required so the note is tied to its origin. There is one defined exception: for a volume discount, the reason code is set to the volume-discount value and, in that case, the preceding invoice reference detail is not required. Outside that exception, the link to the original invoice must be present.
How the process runs end to end
A triggering event occurs (a return, a price correction, a cancellation).
Your accounting system produces the credit or debit note in PINT-AE XML, carrying the correct type code, the reason code, and the preceding invoice reference.
You transmit it to your provider within the prescribed timeframe for the triggering event.
The provider validates it, routes it to the buyer through the Peppol network, and reports the tax data to the FTA at the same time.
Both parties receive confirmation and update their VAT ledgers for the relevant return period.
Credit note values adjust output VAT in the period they fall into, so reconciliation discipline matters. A credit note booked to the wrong period creates a mismatch the FTA can see against the real-time data.
Agent and buyer-issued notes
The framework allows for delegated issuance in defined cases. An authorised agent can issue and transmit credit notes on behalf of the principal. In agreed self-billing cases, the buyer may issue the credit note on behalf of the seller, provided both parties are VAT-registered and meet the conditions in the VAT Executive Regulation. If you use either arrangement, confirm it is set up correctly, because self-billed documents require the buyer to be onboarded to the system.
What to check before go-live
Map your existing note workflow to the PINT-AE fields.
Many ERP systems lack a native field to carry the original invoice reference at the structured-data level. Find that gap now.
Confirm your provider transmits credit and debit notes, not just invoices.
Not every provider package includes adjustment-document transmission by default.
Set reason codes and approval controls.
Because there is no undo, internal sign-off and correct reason coding matter more than before.
Plan a transition protocol.
Decide how you will credit an invoice that was issued on paper before go-live but needs a credit note after go-live. Confirm the handling with your provider or advisor.
Where HLB HAMT helps
Adjustment documents are where the structured-data rules and the VAT reconciliation meet, and the original-invoice linkage is exactly the kind of field most ERP setups do not carry natively. HLB HAMT works across both sides through its advisory practice and the Evatra platform, with the firm’s technology division, HAMT Information Technology, Ministry of Finance accredited service provider for e-Invoicing services in the UAE. Getting the credit note chain right before go-live avoids rejected adjustments and VAT-period mismatches later.
Simplify Credit and Debit Note Compliance
Managing credit notes and debit notes correctly is essential for accurate financial reporting and UAE e-Invoicing compliance. HLB HAMT, helps businesses implement compliant processes, configure ERP systems, and ensure every document meets the latest regulatory requirements.