In the world of business, understanding your financial numbers is crucial. Bookkeeping is not just an administrative task. It is a valuable tool that provides a clear picture of your company’s financial health. With the introduction of Corporate Tax in the UAE, maintaining organised and compliant financial records has become even more important. This article explores the fundamentals of bookkeeping and explains how businesses can maintain accurate records while adapting to the UAE’s Corporate Tax framework.
Bookkeeping: An Overview
Bookkeeping is one of the most fundamental activities for maintaining financial health and transparency. It involves recording financial transactions daily or at regular intervals. These records provide an accurate picture of a company’s financial position and help track where money comes from and where it goes. Maintaining proper bookkeeping records also simplifies tax filing and documentation, while improving cash management and financial forecasting.
Why Compliant Bookkeeping Matters for UAE Corporate Tax
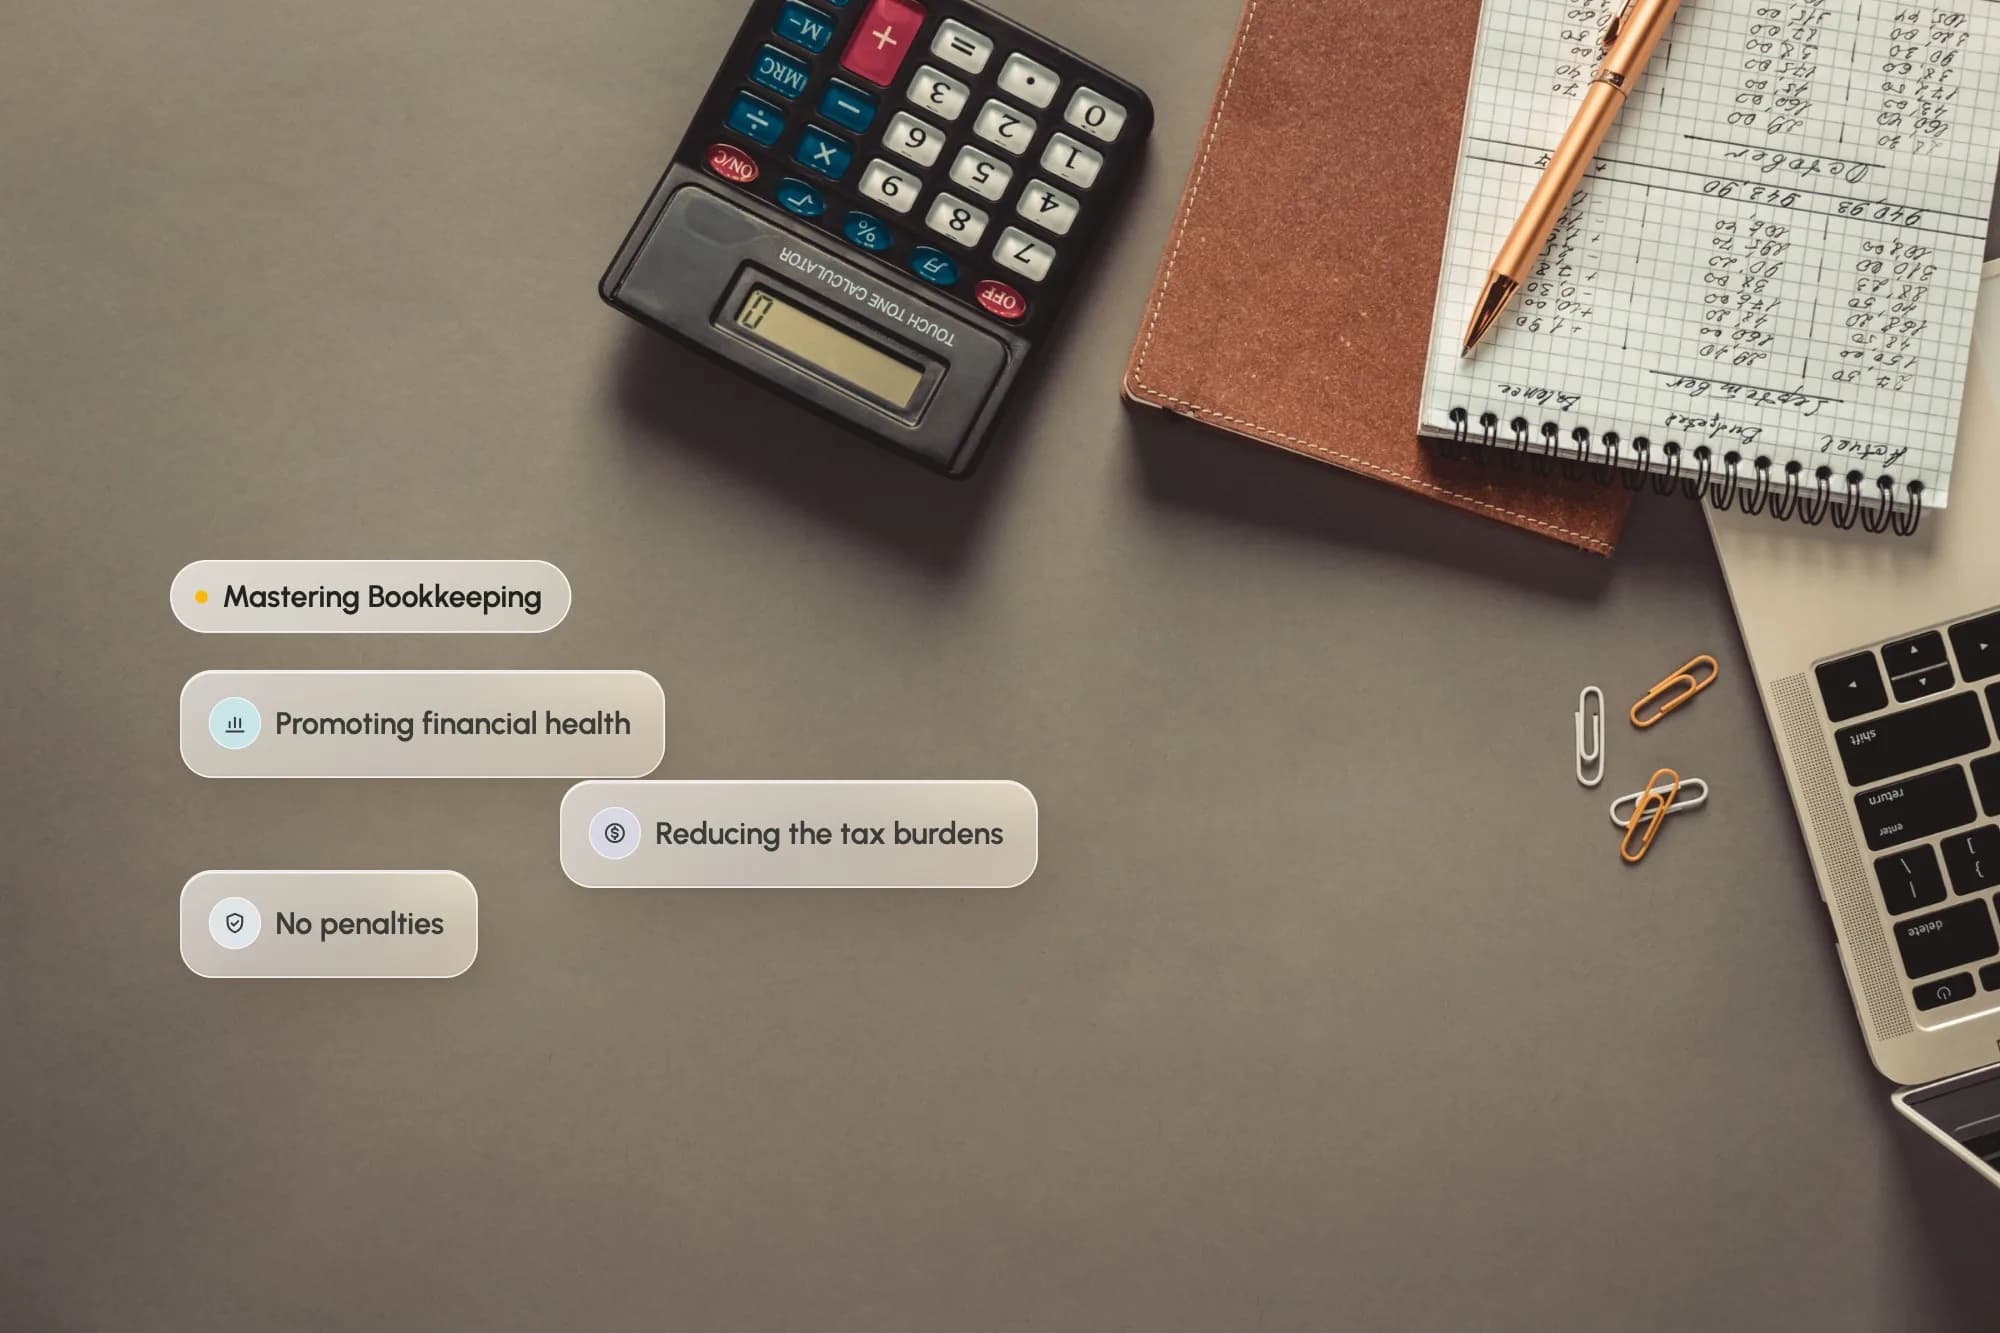
Promoting Financial Health
Bookkeeping helps businesses maintain accurate records of income, expenses and liabilities. These records make it easier to calculate taxable income for the financial year and determine the applicable Corporate Tax liability.
Reducing Tax Burdens
The UAE Corporate Tax framework allows businesses to claim eligible deductions, subject to the applicable rules and conditions. Proper documentation is essential when identifying and supporting these deductions. Accurate bookkeeping records help businesses maintain the evidence required to support their tax positions.
Avoiding Penalties
Maintaining proper accounting records is an important requirement under the UAE Corporate Tax framework. Inadequate records can create compliance issues and increase the risk of penalties. Regular bookkeeping helps businesses maintain financial discipline, support accurate tax calculations and reduce the likelihood of avoidable errors.
Essential Practices for Tax-Compliant Bookkeeping in the UAE
- Recording Detailed Transactions: One of the key requirements of effective bookkeeping is maintaining complete and accurate transaction details. Businesses should record sales, commissions, interest, rent, salaries, supplies and other financial transactions. Detailed entries make it easier to review financial activity and prepare accurate reports.
- Following Accounting Standards: Under Article 4 of Ministerial Decision No. 114 of 2023, taxable persons must prepare financial statements in accordance with the applicable accounting standards. Article 20 of the Corporate Tax Law provides the general rule for determining taxable income. In principle, taxable income is calculated separately for each taxable person based on adequate, standalone financial statements prepared for reporting purposes in accordance with accounting standards accepted in the UAE.
- Systematic Record Maintenance: Every business should establish a reliable system for storing invoices, receipts, contracts, bank statements and accounting records. Organised documentation makes financial reviews and tax-related checks easier.
- Using Accounting Software: Cloud-based accounting and bookkeeping software can simplify transaction recording, improve access to financial information and reduce manual errors. Businesses should select software that suits their operational requirements and supports accurate financial reporting.
- Understanding Tax Implications: Familiarity with Corporate Tax terminology is essential. Businesses should understand concepts such as taxable income, non-taxable income, foreign permanent establishments, participation exemptions and exempt income.
- Meeting Record Retention Requirements: Businesses must comply with the applicable UAE record-retention requirements. Corporate Tax records and supporting documents generally need to be retained for at least seven years following the end of the relevant tax period. Businesses should also consider any longer retention requirements that may apply under other laws or regulations.
- Updating Records Regularly: Bookkeeping records should be updated consistently. Regular updates help businesses identify discrepancies early, maintain accurate financial information and avoid last-minute corrections during tax preparation.
Bottom Line
Prioritising good bookkeeping practices creates a strong foundation for business growth. It supports accurate Corporate Tax calculations, reduces the risk of compliance issues and provides valuable financial insights.
Well-maintained bookkeeping records also support informed decision-making, strengthen investor confidence and make audit preparation easier. Ultimately, accurate financial records contribute to long-term business success in the UAE’s evolving regulatory environment.
HLB HAMT: Your Trusted Partner for Financial Needs!
With in-depth knowledge of the UAE’s bookkeeping and Corporate Tax landscape, our experts provide tailored solutions to meet your business requirements. We go beyond compliance. Our comprehensive services include auditing, business consultancy, taxation, AML/CFT, and HR and payroll services. We support businesses across industries such as logistics, retail, hospitality and healthcare, construction and real estate, and manufacturing and distribution.